My new daughter-in-law thought marrying my son gave her the right to erase the woman who had raised him alone for thirty-five years. She had no idea the $80,000 down payment for their dream house was coming from the flower shop money I had saved one careful dollar at a time. So when she looked me straight in the eye and said, “You’re not really immediate family anymore,” I nodded, went home, and quietly made sure my money respected her definition.
My name is Linda Parker. I was sixty-one and owned a small flower shop in Columbus, Ohio. My husband died when our son, Michael, was four. I raised him alone while building Parker Blooms from a folding table at weekend markets into a modest storefront that eventually paid our bills. There was never much extra. Every school trip, dentist appointment, baseball uniform, and college payment came from weddings arranged at midnight and Valentine’s roses trimmed until my fingers cracked.
Michael grew into a good man—or at least I believed he had. At thirty-five, he married Jessica Reynolds, an interior designer from a family considerably wealthier than ours. I liked her at first. She was polished, ambitious, and affectionate whenever Michael was present. After the wedding, however, something shifted.
Sunday dinners became “couple time.” Christmas plans suddenly revolved around Jessica’s parents. When Michael invited me to brunch, Jessica would somehow turn it into a larger event where I felt like a guest.
Then they found a four-bedroom house in Dublin listed for $615,000.
Michael called me because their savings were short of the down payment they wanted. I offered $80,000 as a gift. Not a loan. I had spent years building a separate savings account from shop profits, partly because I wanted to help him buy a home someday.
Their lender sent me paperwork for a gift letter.
I had not signed it yet.
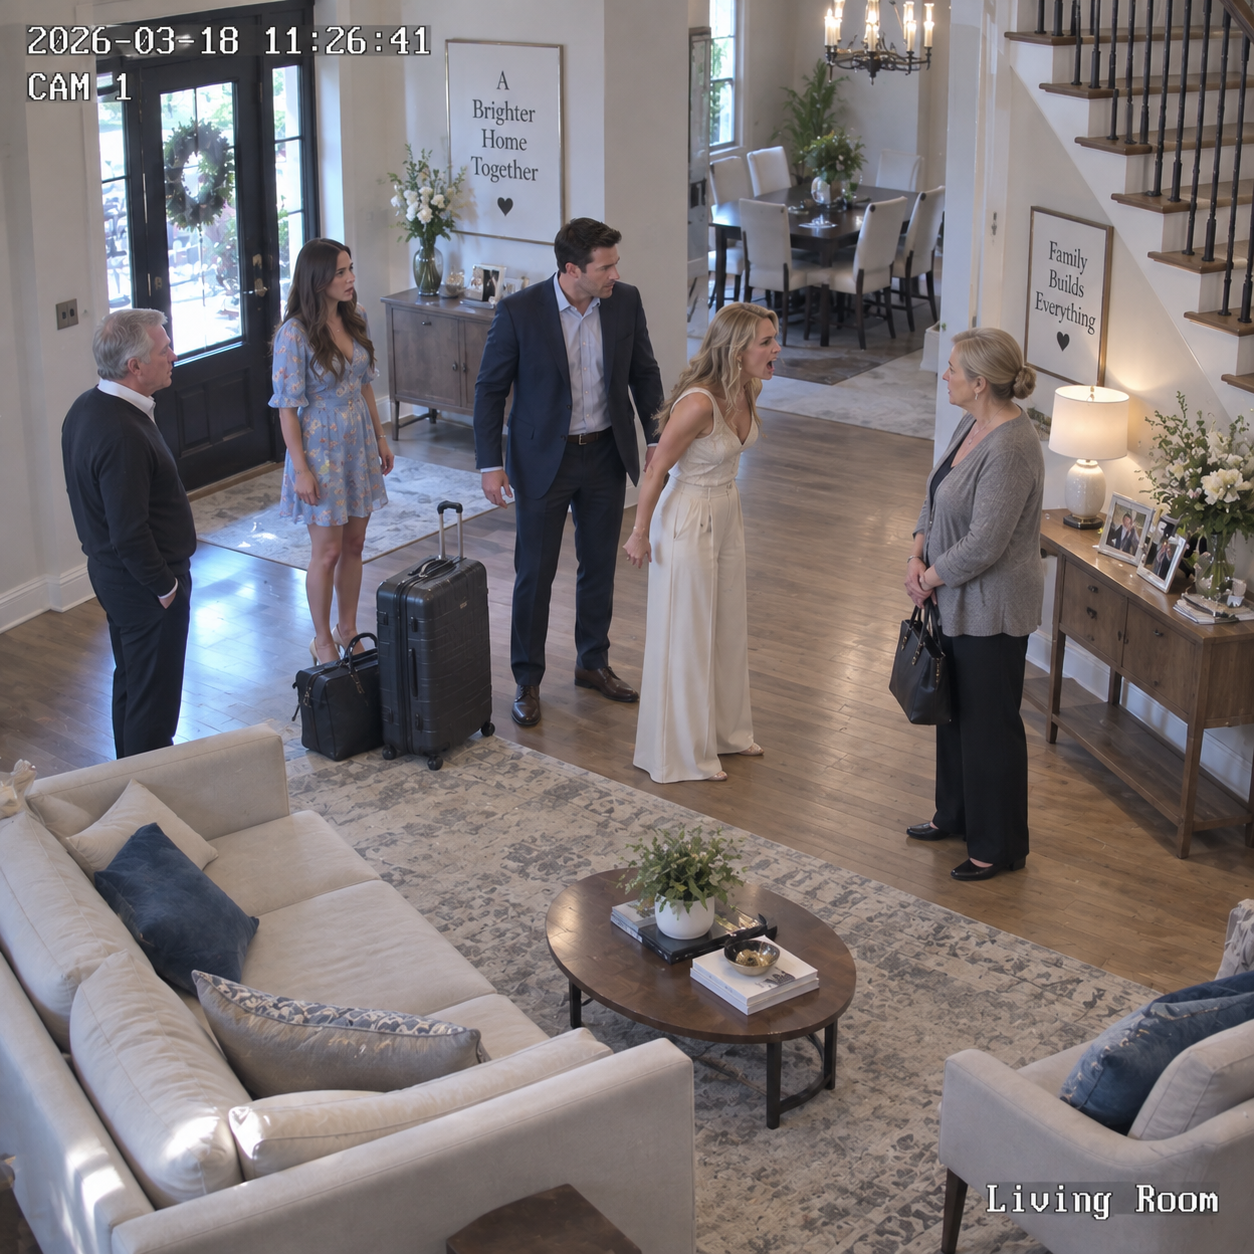
Three days before closing, Jessica hosted dinner for both families. While discussing Thanksgiving, she announced they would celebrate exclusively with her parents because “married couples eventually form their own real family unit.”
I asked whether Michael and I could have breakfast together that morning.
Jessica smiled.
“You have to understand, Linda. You’re not immediate family anymore. Michael has his own family now.”
Michael stared at his plate.
He said nothing.
That silence hurt more than her words.
I finished dinner, hugged my son goodbye, and drove home.
The next morning, I called the loan officer.
“My $80,000 gift has not been transferred yet, correct?”
“Correct.”
“And the gift letter isn’t complete?”
“No, ma’am.”
“Then please remove it from the file. I will not be providing those funds.”
At 10:14, Michael called.
At 10:16, Jessica called.
At 10:18, her father called.
I let all three go to voicemail.
Then Jessica sent one message:
You can’t do this three days before closing.
I looked at the flowers lined across my shop counter and typed back:
I thought I was no longer family.
Michael came to the flower shop that afternoon looking more frightened than angry. Without my $80,000, their financing no longer fit the structure they had planned. They were not suddenly homeless; they were living comfortably in a rented townhouse and had their own savings. But the larger down payment had allowed them to avoid a more expensive loan structure and keep substantial cash available for renovations. I had offered to make their purchase easier. Somehow, within weeks, that offer had become something they treated as already belonging to them.
“Mom, you promised,” Michael said. I put down the ribbon scissors and looked at him. “Yes. I promised because I wanted to help my son and his wife build a home.” He asked what had changed. I almost laughed. “Your wife told me I’m no longer family, and you sat beside her while she said it.” Michael insisted Jessica had only meant that spouses become each other’s primary family. I agreed with that. A marriage should come first. What I did not accept was redefining his mother as disposable while expecting her savings to remain fully included.
Jessica arrived twenty minutes later with her father, Charles. He treated the situation like a contract dispute. He said they had relied on my commitment, that furniture had been ordered, and that withdrawing the gift was “financially irresponsible.” I asked him to show me any signed agreement obligating me to provide the money. There wasn’t one. The lender had specifically required the gift letter because the transfer had not occurred. I had not signed it, and I had never deposited money into their account. Legally and practically, the $80,000 was still mine.
Charles offered to “solve this emotionally” by having Jessica apologize. I told him an apology negotiated to restore financing would mean very little. Jessica became angry and finally said what she had apparently believed all along. “You saved that money for Michael. Whether you like me or not shouldn’t matter.” I answered calmly, “I saved it because I hoped to help him someday. Saving money for a purpose is not the same as transferring ownership.” Michael closed his eyes. For the first time, I think he understood that there was no sentence he could use to make the distinction disappear.
Their original closing was postponed. They had three choices: buy with a smaller down payment and higher monthly costs, use more of their own savings, or walk away within the protections available under their financing contingency. After speaking with their lender and realtor, they chose a smaller loan on a less expensive house rather than draining their reserves. Three months later, they purchased a renovated three-bedroom home for $468,000. It was not the showpiece Jessica had imagined, but it was theirs.
My decision created an explosion in the family. Jessica told relatives I had sabotaged their future. Charles said I was using money to control my adult son. That accusation bothered me because I never wanted my gift to purchase access to Michael. So I made one rule for myself: I would not offer the $80,000 again in exchange for holidays, visits, grandchildren, apologies, or obedience. The offer was finished. Relationship and money would remain separate from that point forward.
Michael stayed away for almost six weeks. Then one rainy evening, he walked into the flower shop five minutes before closing. He did not ask about the money. He picked up a broom and started sweeping fallen leaves and trimmed stems from the floor, something he had done since he was twelve. We worked in silence for ten minutes before he finally said, “I should have spoken up at dinner.”
I looked at him.
“Yes.”
He nodded.
“I thought staying quiet would keep peace with my wife.”
“It kept peace for you.”
He stopped sweeping.
“And made you pay for it.”
For the first time since the wedding, my son had finally understood what actually happened.
Michael and Jessica did not divorce, and I never wanted them to. If anything, the house controversy forced them to confront expectations they should have discussed before marriage. Jessica had grown up in a family where parents financed weddings, houses, vacations, and private-school tuition. In her world, family money flowed downward almost automatically. I had grown up watching every dollar because there was nobody waiting behind me to rescue a bad decision. Neither background was morally superior, but Jessica’s mistake was assuming my savings belonged inside the same system simply because I was Michael’s mother.
Months later, Jessica asked to meet me alone. We sat in a coffee shop where she surprised me by apologizing without mentioning the down payment. She admitted she had felt threatened by how close Michael and I were. “You two had thirty-five years before I arrived,” she said. “I thought becoming his wife meant I had to prove I came first.” I told her marriage was not a ranking system where every new relationship required erasing an old one. She nodded. “I know that now.”
I did not immediately trust her again, but the relationship improved. Thanksgiving that year was split fairly: breakfast with me, dinner with her parents. The next year, we all ate together at Michael and Jessica’s smaller house. Nobody called anyone “immediate” or “extended.” We simply passed the potatoes.
The $80,000 stayed invested.
Two years later, Parker Blooms needed a new refrigeration system and delivery van. For once, I used some of that money on the business that had generated it. The rest went into retirement savings. It felt strangely liberating to spend money on my own security instead of preserving every extra dollar for somebody else’s future.
Michael eventually apologized for assuming I would always sacrifice because I had done it when he was a child. “I think I got so used to you finding a way that I stopped noticing what it cost you,” he said.
That sentence stayed with me.
Parents often create their own invisibility.
We solve problems quietly, then act surprised when grown children begin assuming solutions simply appear.
I had spent thirty-five years making sure Michael never carried the full weight of my sacrifices. That was appropriate when he was five.
It became unhealthy when he was thirty-five.
Three years after the argument, Jessica became pregnant with their first child. When they told me, I cried so hard Michael laughed. A few months later, Jessica asked whether I wanted to help paint the nursery.
Not pay for it.
Not furnish it.
Help paint it.
I arrived in old jeans with two brushes and spent Saturday getting pale green paint in my hair.
At lunch, Jessica handed me a sandwich and said, “I’m glad you’re here.”
There was no condition behind it.
That mattered more than the $80,000 ever could.
When my granddaughter was born, I started a college account with a modest contribution each year. The account was legally structured, documented, and completely separate from my relationship with her parents. I had learned generosity works best when expectations are clear.
Looking back, Jessica’s cruel sentence ended up teaching all of us something useful.
When she said I was no longer family, I did not remove myself from Michael’s life.
I simply stopped allowing my bank account to remain more welcome than I was.
That distinction changed everything.
Money can help people buy houses.
It can pay tuition, fix cars, and make hard seasons easier.
But once money becomes the price someone expects you to pay for belonging, generosity has already been replaced by entitlement.
My son eventually understood that.
Jessica did too.
And I learned the lesson I should have learned years earlier:
Love can be unconditional.
Financial support does not have to be.