My son told me, I’m not your servant. He thought his wife could keep using my money like nothing had changed. So I canceled the card she was using. Hours later, he called me furious…
“I’m not your servant, Mom.”
My son’s words landed harder than I expected.
I’m Patricia Miller, sixty-three, a widow living outside Phoenix, Arizona. My son, Ryan, was thirty-eight, married to Ashley, and for the past three years I had been helping them financially whenever life became “too expensive.”
That Tuesday morning, I had called Ryan because I needed a ride home after a minor outpatient procedure.
“You said you were free,” I reminded him.
“Plans changed.”
“I only need twenty minutes.”
Ryan sighed. “I’m not your servant. Call somebody else.”
Then he hung up.
I sat there staring at my phone.
Ten minutes later, a notification appeared from my credit-card account.
$286.40.
A designer department store.
Ashley was using the authorized-user card connected to my account.
I had given it to her eighteen months earlier for groceries and emergencies after Ryan temporarily lost his job. Somehow, “emergencies” had expanded into restaurants, cosmetics, clothing, and weekend purchases.
I had complained twice.
Ryan always promised they would reimburse me.
They rarely did.
I called the card company.
“I want to remove an authorized user and deactivate her card.”
The representative verified my identity.
A few minutes later, it was done.
I didn’t call Ryan.
I didn’t call Ashley.
I ordered a rideshare home.
At 4:17 P.M., my phone rang.
Ryan.
I answered.
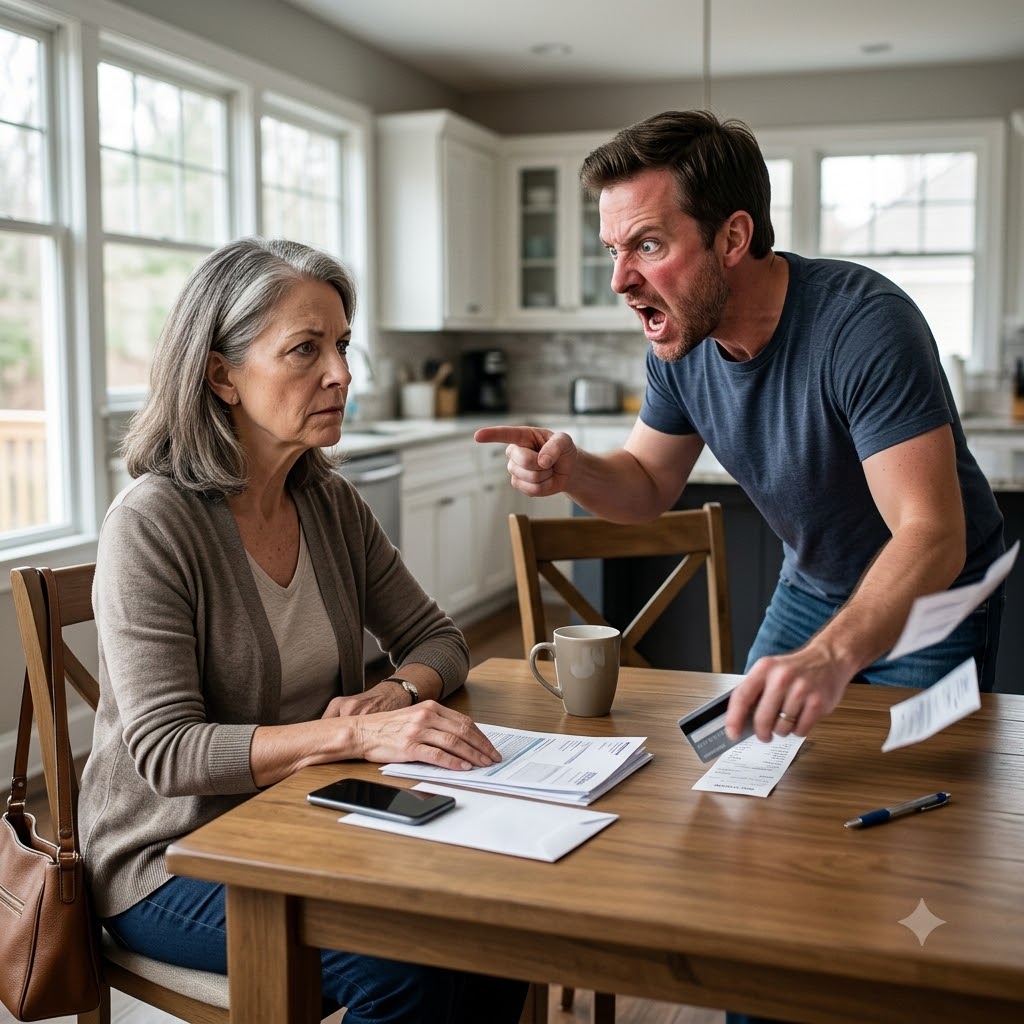
“What did you do?” he shouted.
“Hello to you too.”
“Ashley’s card was declined!”
“It isn’t Ashley’s card.”
Silence.
Then his voice became louder.
“She was standing at the register with people behind her!”
“That sounds uncomfortable.”
“You embarrassed my wife!”
“No, Ryan. I stopped paying for her purchases.”
He accused me of being petty because he wouldn’t drive me home.
That wasn’t true.
His comment had simply forced me to notice something I should have noticed years earlier.
He didn’t want the responsibilities of being my son.
But he still expected the benefits of being mine.
“You need to reactivate it,” he demanded.
“No.”
“Mom, don’t start this.”
“I’m not starting anything.”
“What is that supposed to mean?”
“It means your wife can spend your money now.”
Ryan went silent.
Then he said, “Fine. If that’s how you want this relationship to be.”
Before I could answer, he hung up.
I thought the argument was finished.
It wasn’t.
That evening, I downloaded eighteen months of statements.
By midnight, I had highlighted every purchase Ashley had made.
The total made my stomach drop.
$21,846.
And when I looked closer, I found something even worse.
Several charges had been made on days Ashley had specifically told me she wasn’t using my card.
The next morning, I spread eighteen months of statements across my dining table. I wasn’t interested in turning every grocery run into a criminal investigation. I had willingly made Ashley an authorized user, and I knew that meant many purchases could legitimately become my responsibility to the card issuer. What bothered me was the pattern. There were department stores, expensive dinners, beauty appointments, hotel deposits, concert tickets, and hundreds of dollars in online shopping. The card I had provided for groceries and emergencies had quietly become part of their household budget.
I called my financial adviser, Mark Reynolds, and asked him to help me understand exactly how much support I had given Ryan and Ashley over the previous three years. The answer was worse than I expected. Beyond the card charges, I had paid $9,000 toward their car when Ryan lost his job, covered several months of preschool for my granddaughter Chloe, paid an emergency plumbing bill, and transferred money whenever Ryan said they were short before payday. Mark asked one uncomfortable question: “Patricia, how much of this have they repaid?” I already knew the answer. Almost none of it.
That evening, Ashley called. Unlike Ryan, she didn’t shout. “Patricia, I think there’s been a misunderstanding.” “About what?” “The card. Ryan told me you said I could use it for household expenses.” I paused. I had told Ashley groceries and emergencies. I had never authorized unlimited personal spending. Ashley insisted Ryan had repeatedly told her not to worry because I was financially comfortable. That irritated me, but it also revealed something important. Ryan had been making promises with my money. “The card is canceled,” I said. “I’m not reactivating it.” Ashley became defensive. “What are we supposed to do?” “Use your income.” “We have bills.” “So do I.”
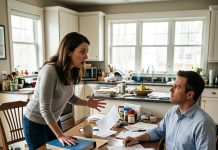
Ryan came to my house two days later. He walked into the living room holding several printed statements. “You went through everything?” he asked. “It’s my account.” “You’re acting like Ashley stole from you.” “I haven’t said that.” “Then why are you highlighting purchases?” I looked at him. “Because I wanted to understand what I’ve been paying for.” Ryan started explaining. Their mortgage had increased because of taxes and insurance. Chloe’s childcare was expensive. Ashley had student loans. His commission income fluctuated. The card had become a cushion. “Then why didn’t you ask me?” I said. He looked away. “Because you always said family helps family.”
That sentence almost made me laugh. “Family helps family? Yesterday I needed one ride after a medical procedure, and you told me you weren’t my servant.” Ryan’s face tightened. “So this is punishment.” “No. Punishment would be trying to hurt you. I’m simply stopping an arrangement that no longer works for me.” He told me I was overreacting. I told him the card would remain canceled.
Then I asked about several charges Ashley had denied making. Ryan stared at the statements for several seconds. “Those weren’t Ashley’s.” “Then whose were they?” He rubbed his forehead. “Mine.” I froze. Ryan admitted he had saved the card information in several apps and occasionally used my account when his own card was near its limit. Ashley genuinely hadn’t known about some of the charges. “How much debt do you have?” I asked. “It’s manageable.” “How much?” He finally answered. Between their cards and a personal loan, they owed almost $58,000.
For the first time, I understood why canceling one card had caused such panic.
It wasn’t about Ashley being embarrassed at a register.
My money had been holding together a financial life that was already beginning to collapse.
I could have paid the debt.
That was the dangerous part.
After my husband died, I sold a small rental property we had owned for years. Combined with my retirement savings and pension, I was financially comfortable. Writing Ryan a check for $58,000 would have hurt, but it wouldn’t have ruined me.
Three years earlier, I probably would have done it.
This time, I didn’t.
Instead, I offered to pay for one appointment with a nonprofit credit counselor. Ryan initially refused. He said he and Ashley could handle their own finances. I reminded him that handling their own finances was exactly what I wanted.
Ashley convinced him to go.
Their situation wasn’t hopeless, but it required changes they had avoided for years. Ryan’s commission income was inconsistent, yet they budgeted as if every month would be a good month. They had two expensive vehicles, frequent restaurant spending, subscriptions they barely used, and credit-card balances carrying high interest.
The counselor helped them create a realistic plan.
They sold Ryan’s truck and bought an older used SUV with a much smaller payment. Ashley stopped using buy-now-pay-later services. They canceled several subscriptions, reduced restaurant spending, and created a monthly budget based on Ryan’s lower-income months instead of his best ones.
I maintained one boundary.
No routine cash.
I still bought Chloe birthday and Christmas presents. I occasionally watched her after school. When she needed new glasses, I offered to help because that was something directly for my granddaughter.
But I never reactivated Ashley’s card.
The first two months were ugly.
Ryan barely called me.
When he did, our conversations were short and uncomfortable.
Then, one Saturday morning, he appeared at my door.
“Can I come in?”
That question mattered.
“Of course.”
He sat at my kitchen table.
“I owe you an apology.”
I waited.
“Not just for the card.”
He looked down at his hands.
“For what I said that day.”
I knew exactly what he meant.
“I’m not your servant.”
Ryan exhaled.
“You needed me for twenty minutes. I couldn’t even do that without acting like you were bothering me.”
“Yes.”
“But I had no problem letting you pay hundreds of dollars every month.”
“Yes.”
He gave a painful little laugh. “You’re really going to make me say all of it, aren’t you?”
“I think you need to.”
So he did.
He admitted that after years of my helping, he had stopped viewing my money as generosity. It had become part of his calculations. If the car needed repairs, Mom could help. If childcare increased, Mom could help. If the credit cards got too high, Mom could help.
“And when you canceled that card,” he said, “I wasn’t angry because Ashley was embarrassed.”
“I know.”
“I was scared.”
That was the first completely honest thing he had said about the situation.
Ten months later, Ryan and Ashley had reduced their consumer debt significantly. They weren’t debt-free, but they were finally moving in the right direction. Ryan had also taken a more stable salaried position, even though it offered less potential upside than commission sales.
Ashley apologized too.
She admitted she should have asked me directly what the card was intended for instead of relying on Ryan’s interpretation.
I accepted her apology.
I didn’t give the card back.
Almost a year after our original argument, I had another outpatient appointment.
I didn’t ask Ryan for a ride.
He remembered anyway.
At 7:15 that morning, he pulled into my driveway.
When I opened the door, he was leaning against his car holding two coffees.
“Ready?”
I smiled.
“You don’t have to do this.”
“I know.”
The drive home later took twenty-three minutes.
Neither of us mentioned money.
When he helped me inside, I thanked him.
He shrugged.
“You’re my mom.”
That sentence meant more to me than every dollar I had spent on him.
Canceling Ashley’s card didn’t fix our family.
It simply forced all of us to see what had happened.
Ryan had once told me he wasn’t my servant.
He was right.
I never wanted a servant.
I wanted a son who understood that family support was supposed to travel in both directions.
And eventually, that was exactly what I got.