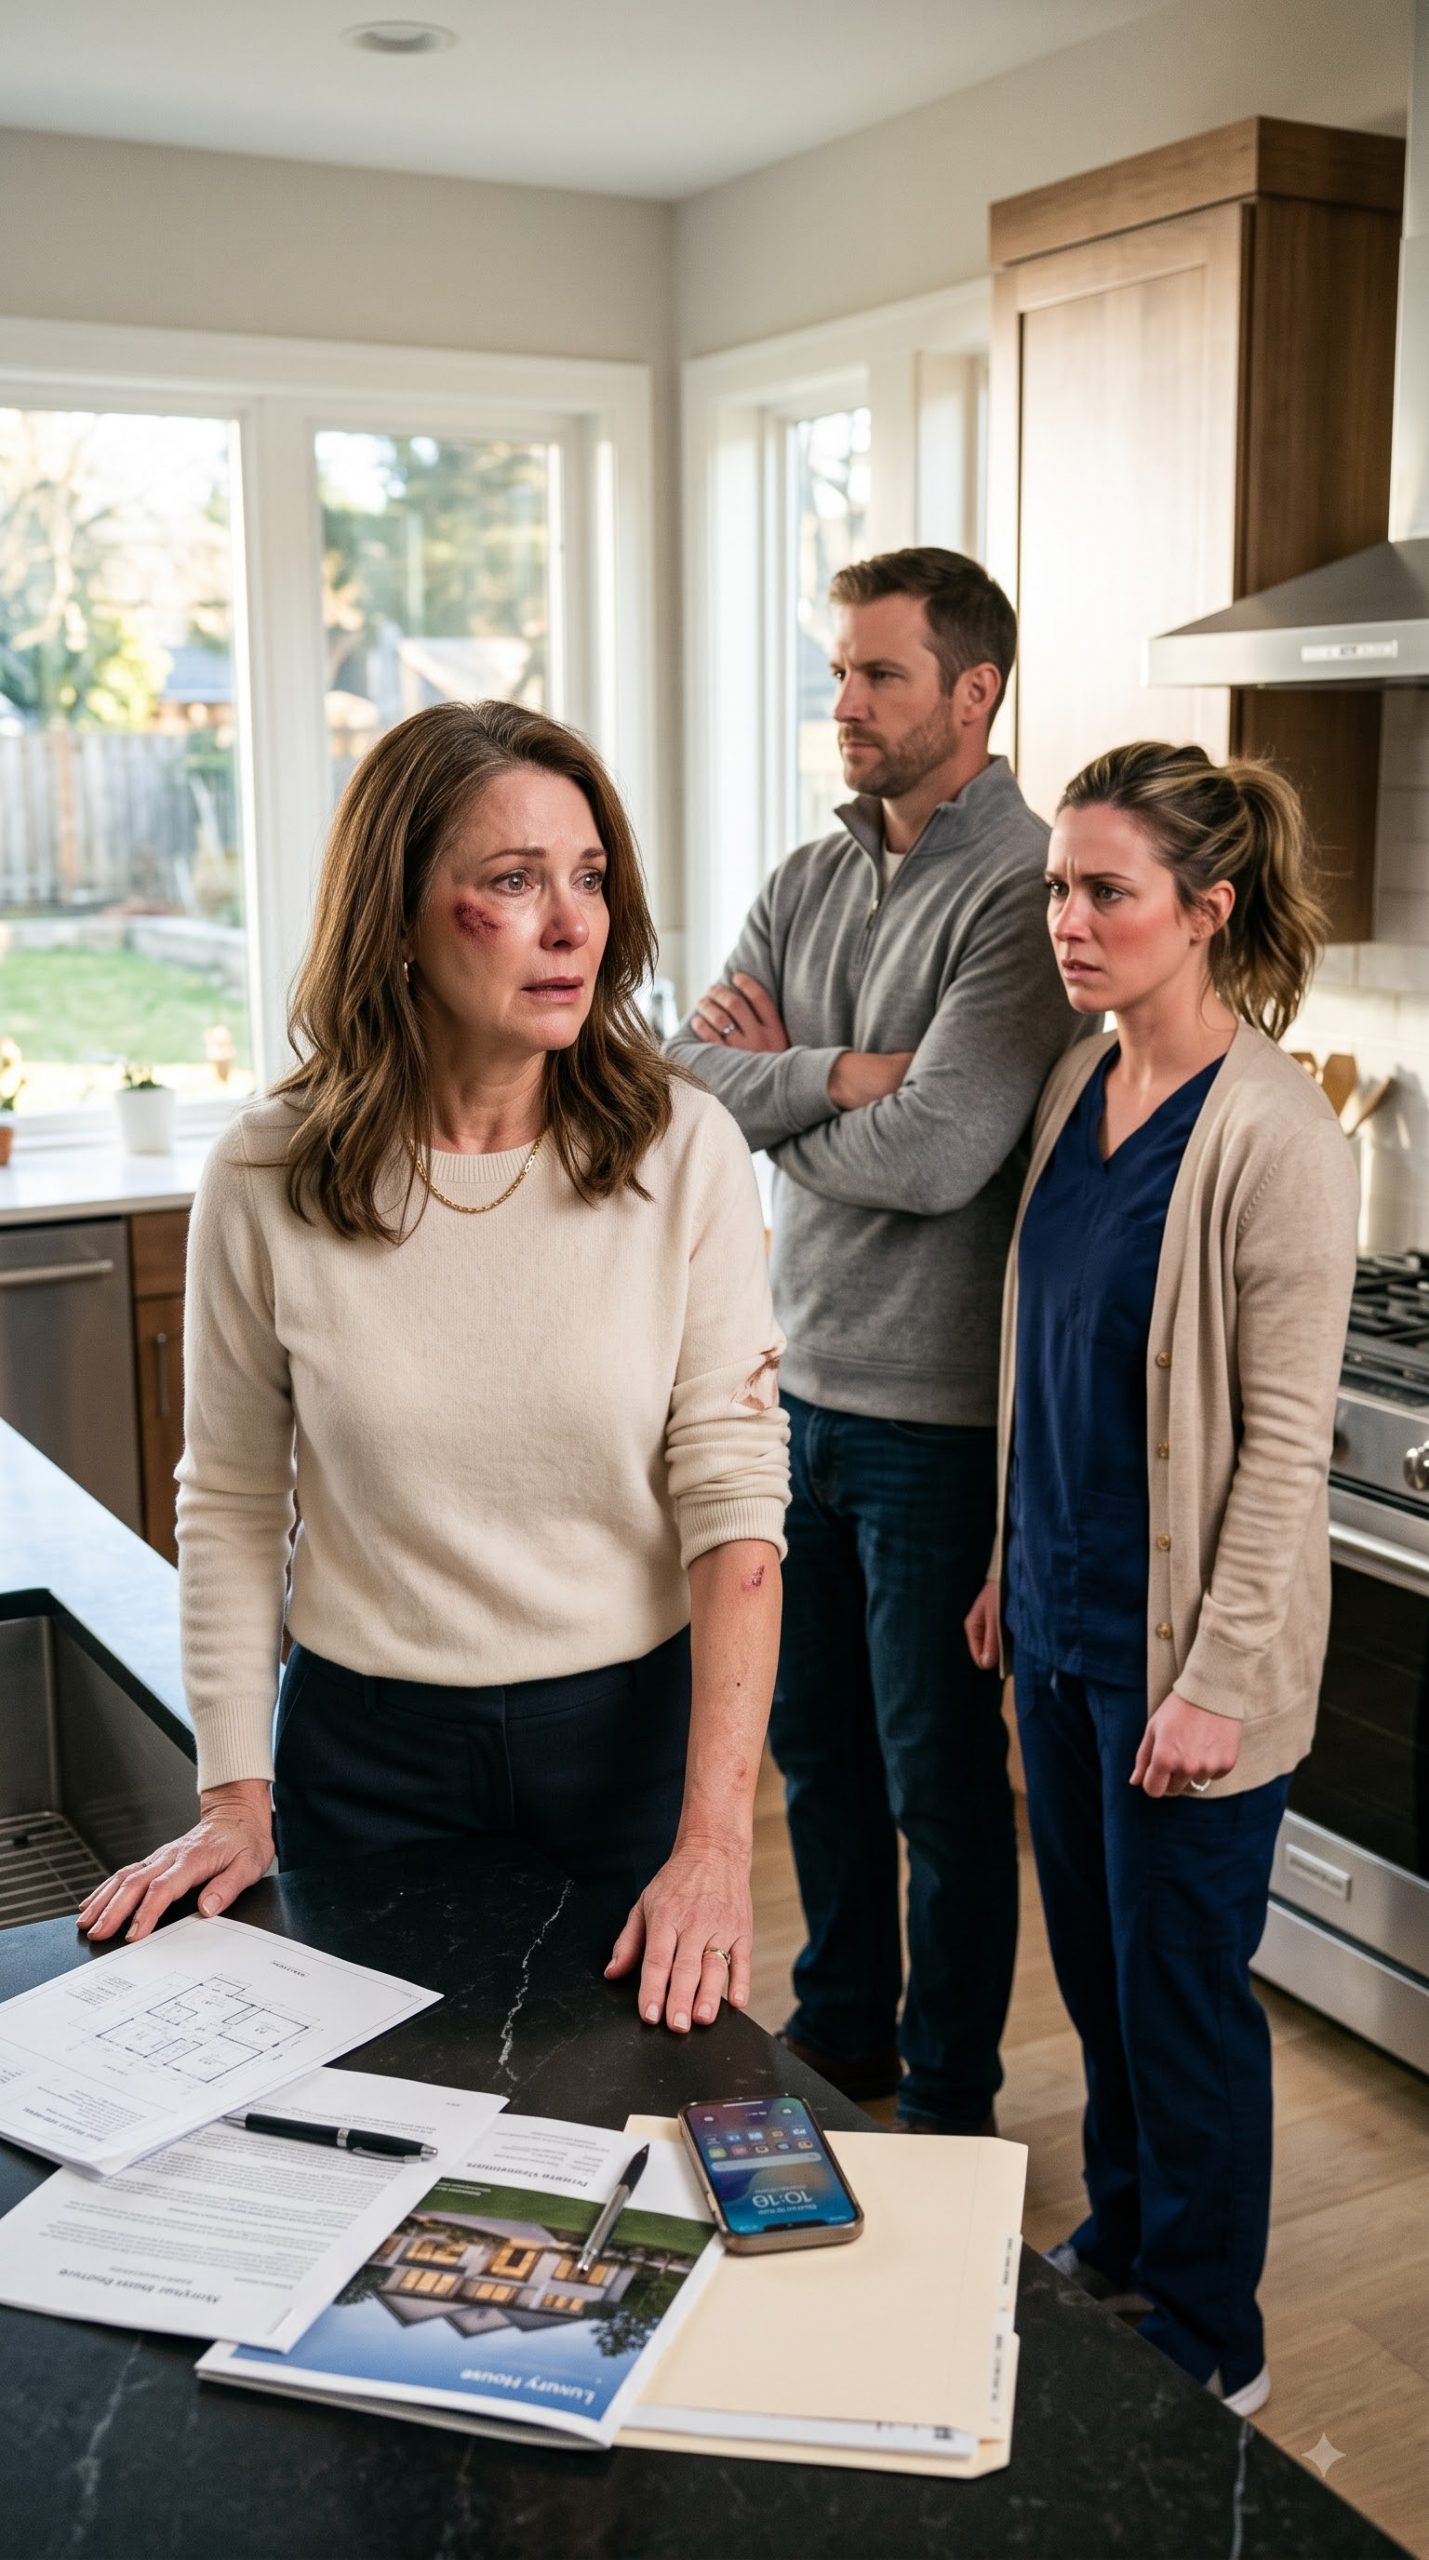
My daughter-in-law shoved me hard enough to send me to urgent care. Hours later, my son texted, “Stay away from us.” I said, “Okay,” withdrew the $95,000 I had promised for their new house, and their mortgage collapsed. Then the lender asked one question that made my blood run cold.
The pain hit before I understood Ellie had actually shoved me.
My hip slammed into the edge of their kitchen island, and I went down hard enough to knock a barstool sideways. For a second, I couldn’t breathe.
Ellie stood over me, pale and furious.
“Get out of my house.”
I stared at my son’s wife. “You just put your hands on me.”
“You were snooping.”
I hadn’t been snooping. She had left a mortgage folder open on the counter while I was dropping off paperwork for the $95,000 I had promised toward their new house. On top was a page titled Gift Letter.
My name was printed beneath a signature I had never written.
I reached for it.
Ellie grabbed my wrist.
When I refused to let go, she shoved me.
I drove myself to urgent care with a bruised hip, a swollen wrist, and one question pounding in my head: Why was my signature on their loan file?
Three hours later, my son, Ryan, finally texted.
Not “Are you okay?”
Not “What happened?”
Just: Stay away from us. Ellie says you attacked her in our kitchen. We’re done.
My hands shook as I typed one word.
Okay.
Then I called their mortgage officer.
I told her the $95,000 gift was withdrawn immediately. I would not provide funds, sign any letter, or guarantee anything connected to Ryan or Ellie.
There was a long silence.
Then she said, “Mrs. Bennett, I need to ask you something very carefully.”
My stomach tightened.
“Did you authorize them to use your home as additional collateral?”
That question changed everything. I thought I was withdrawing a gift after being assaulted. I had no idea the mortgage file contained something far more serious—or that my own son already knew exactly what had been submitted. The rest of what happened is in the comments.
“No,” I said. “Absolutely not.”
The loan officer, Melissa Grant, lowered her voice.
“Then please do not call Ryan or Ellie. I’m flagging the application and sending it to our fraud department.”
My injured wrist started throbbing again.
Melissa explained that their file included more than my $95,000 gift letter. There was also a notarized “family support agreement” stating I would cover twelve months of payments if Ryan and Ellie fell behind.
I had never seen it.
Worse, an attachment listed my paid-off home in Columbus as a secondary source of repayment.
“That doesn’t mean they own your house,” Melissa said quickly. “But the document was used to strengthen the loan.”
“Whose signature is on it?”
“Yours.”
I almost laughed.
Twenty minutes later, Ryan called.
“Mom, what did you do?”
No apology. No concern.
“You told me to stay away.”
“You canceled the money?”
“Yes.”
“You can’t do that this late! We close Friday.”
I looked at the urgent-care bracelet still around my wrist.
“Then you should have thought about that before your wife shoved me.”
His voice dropped.
“Ellie said you fell.”
“She lied.”
Silence.
Then he said something that chilled me.
“Just call the bank back and tell them you misunderstood the paperwork.”
So he knew there was paperwork.
I asked, “What exactly am I supposed to say I misunderstood?”
Ryan hung up.
An hour later, Ellie arrived at my house with him.
I didn’t open the door.
Through the camera, I watched Ryan hold up a thick envelope.
“We just need one signature to fix this.”
Ellie stood behind him with her arms folded.
My son kept ringing the bell.
“Mom, if this loan dies, we lose the deposit. We could lose everything.”
I called my attorney, Rebecca Sloan, and put her on speaker.
“Do not sign anything,” she said. “Ask him to leave.”
Ryan heard her voice through the door.
His face changed.
Then Ellie stepped toward the camera.
“You promised to help us.”
“I promised money,” I said through the door. “I did not promise my house.”
Ryan snapped, “Nobody is taking your house!”
Rebecca cut in.
“Then you won’t mind if the lender sends me the full application.”
Neither of them answered.
That was the moment I knew this was bigger than a forged gift letter.
The next morning, Rebecca obtained copies from the lender.
She called me before 8:00 a.m.
“Margaret, Ryan didn’t just submit your house information.”
I sat down.
“What did he do?”
“He attached a home-equity application in your name.”
My mouth went dry.
“For how much?”
“Two hundred and eighty-six thousand dollars.”
Then Rebecca said the part I never expected.
“Ellie didn’t prepare it. Ryan did.”
What do you think will happen next? I’d love to hear your honest guess or reaction “I’d love to hear your opinions – your comments really make me happy and inspire me to keep writing.”
For several seconds, I couldn’t speak.
Ryan had been the one person I was still trying to protect in my mind.
I could understand Ellie panicking. I could understand her lying after she shoved me. I could even understand my son making the cowardly choice to defend his wife before hearing my side.
But a $286,000 home-equity application in my name was not panic.
It was planning.
Rebecca told me not to confront either of them. She contacted my bank’s fraud department, froze pending credit requests tied to my property, and helped me file a police report about both the assault and the suspected forged documents.
By noon, the mortgage company formally denied Ryan and Ellie’s loan.
That was when the messages started.
Ryan: You ruined our future.
Ellie: I hope you’re proud of yourself.
Ryan: We already put $18,000 down.
Not one message asked about my wrist.
Then Ryan sent a photo of the envelope he had brought to my door.
Inside was an affidavit saying I had “voluntarily participated in all financial arrangements” and that any disagreement resulted from “confusion following medication.”
Medication.
Six months earlier, I had knee surgery. Ryan stayed with me for a week and helped organize bills, insurance forms, and online accounts while I recovered.
Rebecca asked one question.
“Did he have access to your Social Security number, phone, and property records?”
“Yes.”
The bank soon confirmed someone had begun a HELOC application four months earlier using my information. It stalled when extra identity verification was required. Two weeks later, a second application appeared through another lender.
The email address looked like mine but had one extra letter.
The phone number belonged to a prepaid line.
Ryan had tried more than once.
Then Ellie’s attorney called Rebecca.
Ellie wanted to make a statement.
She admitted she knew Ryan had created the fake gift letter and family support agreement. She had signed documents knowing my signature had been copied.
But she claimed Ryan told her I had approved everything and simply hated “formal paperwork.”
I didn’t believe her until she turned over text messages.
Ryan had written to a loan broker named Coleman: Mom’s house is clean. No mortgage. We only need enough out of it to clear the cards and make the new place work.
Coleman replied: Need her verification or a workaround.
Ryan: I can handle verification.
There it was.
The real reason they were desperate to close on a house they could barely afford.
They were already drowning in debt: nearly $74,000 in credit cards, a personal loan, two missed car payments, and a failed investment Ryan had hidden from everyone, including Ellie.
My $95,000 was supposed to be their down payment.
Ryan had turned it into part of a larger escape plan.
When Ellie discovered the debt a month before closing, Ryan told her that if the loan failed, they would lose everything. She chose to help him fake the gift documents.
Then she saw me reading the folder and panicked.
That explained the shove.
It did not excuse it.
Police interviewed both of them.
Ellie was charged in connection with the assault after my urgent-care records, photographs, and a neighbor’s doorbell footage supported my account that I left their home injured immediately after the argument.
The financial case took longer.
Ryan insisted I had verbally authorized him to “handle everything.”
That story collapsed under the timestamps.
One supposed electronic approval from me was submitted while I was attending a charity board meeting across town. Another came from an IP address linked to Ryan’s apartment.
The notary named on one document denied ever meeting me.
Coleman, the broker, handed investigators his messages with Ryan.
Eventually, Ryan accepted a plea agreement involving identity theft and attempted financial fraud. The exact penalties mattered less to me than the outcome: the documents tied to my property were voided, the false credit activity was corrected, and protections were placed on my accounts.
Ellie and Ryan separated before the case was finished.
She sent me a six-page handwritten apology.
She apologized for shoving me, lying about it, and signing documents she knew were wrong.
She also wrote something I could not dismiss: she had spent years believing that whenever she and Ryan made a financial mistake, I would eventually rescue them.
She was right.
I had helped with nursing-school tuition.
I had covered rent when Ryan lost a job.
I had paid off one of their cars after the baby was born.
I thought I was helping them become stable.
Instead, I had helped them avoid consequences.
I never answered Ellie’s letter.
Forgiveness and access are not the same thing.
Months later, Ryan called me.
His voice sounded smaller than I remembered.
“Mom, I know I destroyed this.”
“Yes,” I said.
“I kept thinking I could fix everything before you found out.”
“You were going to fix your life with my house.”
He started crying.
So did I.
But I did not offer money.
“I love you,” I told him. “But loving you does not require me to finance your choices.”
For once, he didn’t argue.
I kept my home.
The $95,000 stayed in my account.
A year later, I used part of it to fund a small nursing scholarship at the community college Ellie had once attended. No family names. No conditions.
Just help given where help could actually do good.
People sometimes ask whether I regret withdrawing the money that cost my son his house.
I correct them.
I did not cost Ryan a house.
I stopped paying for one after his wife hurt me and after he chose deception over honesty.
The loan denial was not revenge.
It was the first consequence I finally allowed him to face.
And the word I texted that night—Okay—became the most important promise I ever kept to myself.